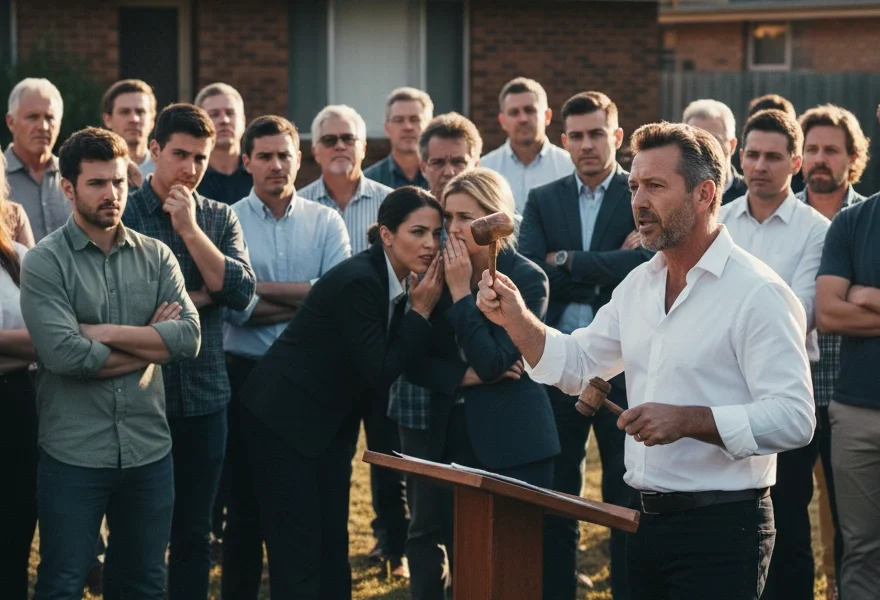
Let us be clear upfront: not all real estate agents are out to get you. Plenty of agents do an honest job and genuinely want to match buyers with the right properties. But the auction system in Australia is fundamentally designed to benefit sellers, and agents work for sellers. Their commission is a percentage of the sale price. The higher you pay, the more they earn.
That basic incentive structure means there are things agents will never volunteer to tell you — not because they are villains, but because telling you would work against their client’s interests. And sometimes, their own.
This guide pulls back the curtain on what actually happens before, during, and after auction day, so you can walk in with your eyes open and your wallet protected.
The Price Guide Is Often a Fantasy
This is the big one, and it has a name: underquoting. It is the practice of advertising a property at a price significantly lower than what the agent genuinely expects it to sell for. Despite being illegal under Australian Consumer Law in every state and territory, it remains one of the most widespread complaints in the real estate industry.
Here is how it works in practice. An agent lists a three-bedroom house with a price guide of $900,000 to $980,000. You do your research, get your finance pre-approved at $1 million, and turn up on auction day feeling prepared. The bidding opens at $950,000 and blows past $1.1 million within minutes. You are standing there with your hand in your pocket wondering what just happened.
What happened is that the agent likely knew the property would sell for well above the quoted range. But by advertising it lower, they attracted more buyers to inspections, created more competition, and drove a higher final sale price.
A recent investigation found that roughly 30 per cent of auctioned properties sold for 10 per cent or more above the quoted price guide. That is not competitive bidding getting carried away — that is a systemic gap between what agents advertise and what they expect.
Why agents do it
The logic is brutally simple. If an agent quotes a property realistically at $1.1 million, they might attract 5 serious buyers. If they quote it at $900,000, they attract 15. Ten of those buyers cannot actually afford the property at its real value, but they do not know that yet. Their presence on auction day creates an atmosphere of intense competition that pushes the remaining serious bidders to stretch beyond what they might otherwise pay.
As one Melbourne property finance broker put it, the more people an agent can drive to an auction on a Saturday morning, the more urgency they create among the buyers who can actually afford the higher price. Even if 99 out of 100 people there cannot afford the property, you would never be able to tell — and the pressure affects everyone.
How to protect yourself
Do not rely on the agent’s price guide as your primary indicator of value. Instead, do your own comparable sales research. Check recent sale prices for similar properties in the same suburb on sites like realestate.com.au, Domain, or CoreLogic. Look at properties with similar bedrooms, bathrooms, land size, and condition that sold within the last three to six months.
If the agent is quoting significantly less than what comparable properties have recently sold for, that is a red flag. You can ask the agent to justify their advertised price with specific comparable sales data. In most states, agents are required to provide this information if asked. If you believe you have been underquoted, you can report it to your state’s consumer affairs body — NSW Fair Trading, Consumer Affairs Victoria, or the equivalent in your state.
Better yet, attend several auctions in your target area before you plan to bid on one. Watch what happens. See how the price guide compares to the final sale price. This experience alone is worth more than any amount of online research.
The Agent Works for the Seller, Not You
This sounds obvious when stated plainly, but it is remarkable how often buyers forget it in the heat of the moment. The selling agent is legally and financially obligated to get the best possible price for the vendor. Every friendly conversation, every helpful suggestion, every reassuring smile is filtered through that obligation.
When an agent tells you there is strong interest in the property, they may be telling the truth — or they may be creating urgency to encourage you to bid higher. When they suggest you might want to put in a pre-auction offer, they are trying to establish a floor price before other bidders even show up. When they call you the night before the auction to check if you are still coming, they are counting their bidder pool.
None of this is illegal or even unethical in most cases. It is simply the reality of an adversarial system where the agent’s interests are aligned with the seller’s, not yours.
What they will not tell you about your competition
Agents are masters at managing information asymmetry. They know who the serious buyers are, roughly what each buyer can afford, and who is most emotionally invested in the property. You know almost nothing about your competition.
Before auction day, the agent will have had private conversations with multiple potential buyers. They know if only two people are genuinely interested or if there are eight registered bidders. They will rarely share this information with you directly because uncertainty works in the seller’s favour. If you knew you were the only serious buyer, you would bid very differently than if you believed you were competing against five others.
The assisting agent on auction day
On auction day, you will often notice an agent who mingles with the crowd, stands near potential bidders, and occasionally makes encouraging comments. This is the assisting agent, and their job is to keep the energy up and encourage bids.
They might lean in and say things like “you are so close” or “just one more bid and I think you have got it” or “I would hate to see you lose this one.” These comments are designed to trigger emotional responses. The assisting agent is not your friend — they are working for the vendor, against your financial interests.
The Reserve Price Is a Moving Target
Most buyers assume the reserve price — the minimum the vendor will accept — is set well before auction day. In reality, in most states the vendor can adjust the reserve right up until the auction begins, and in some cases even during the auction itself.
This creates a scenario that can be deeply frustrating for buyers. Say a property is quoted at $1 million to $1.1 million. The vendor originally sets a reserve of $1.15 million. But on the morning of the auction, the agent reports back that interest has been exceptionally strong. The vendor decides to raise the reserve to $1.2 million.
You, the buyer, have no visibility into any of this. You have done your research based on the price guide, arranged your finance, and prepared to bid up to $1.15 million. The property gets passed in because nobody hit the new reserve, and you are left confused about what just happened.
Victoria is attempting to address this with Australian-first legislation expected to pass in 2026 that will require vendors to publish their reserve price at least seven days before auction. If enforced effectively, this would be a significant win for transparency. Other states have not yet followed suit.
What you can do: If a property is passed in at auction and you were the highest bidder, you have the right of first negotiation with the vendor. This is actually a strong position to be in because the pressure shifts — the vendor now knows their property did not sell publicly and they need to negotiate. Do not let the agent rush you. Take your time, stick to your limit, and remember that a passed-in property often settles for less than the vendor originally hoped.
Dummy Bidding and Vendor Bids
Dummy bidding — where people who have no genuine intention of buying place bids to inflate the price — is illegal in every Australian state and territory. The Real Estate Institute of Australia (REIA) has been vocal about stamping out the practice, and penalties can be severe. But vendor bids, which serve a similar purpose, are perfectly legal when properly declared.
A vendor bid is placed by the auctioneer on behalf of the seller to get the bidding moving or to push it closer to the reserve price. The auctioneer is required to declare vendor bids, but this declaration can be easy to miss in the fast-paced atmosphere of an auction. You might hear “I have a vendor bid” mentioned once, quickly, before the bidding continues at pace.
The practical effect is that vendor bids create the illusion of competition. If the opening bid is a vendor bid and you follow with a genuine bid, it can feel like you are competing against another buyer when you are actually the only real bidder in the room.
How to spot them
Listen carefully for the auctioneer’s declarations. In most states, the auctioneer must clearly announce any vendor bid. If you miss it, you can ask — there is nothing wrong with pausing the auction to request clarification on whether a bid was genuine or a vendor bid.
Also watch the auctioneer’s eyes. When a genuine bid comes from the crowd, the auctioneer will look at the bidder. When a vendor bid is placed, the auctioneer often looks at the agent or down at their notes, because there is no real person to acknowledge.
Your Emotions Are Being Weaponised
The entire auction process is engineered to create emotional pressure. The public setting, the fast pace, the countdown language (“going once, going twice”), the crowd watching — all of it is designed to push you toward impulsive decisions.
Auctioneers are trained performers. They use volume, pace, humour, and dramatic pauses to control the room’s energy. When bidding slows, they will make comments designed to reignite urgency. When you hesitate, the assisting agent will be at your elbow with encouraging words.
The psychology is well understood. In a private negotiation, you have time to think, consult your partner, run the numbers again, and sleep on it. At auction, you have seconds. And research consistently shows that people make worse financial decisions under time pressure and social scrutiny.
The tactics they use
Suggesting higher bid increments. The auctioneer might call for bids in $10,000 increments when you would prefer $5,000 or even $1,000. You are not obligated to follow their suggested increment — you can bid any amount you choose. Smaller bids slow the auction down and signal to other bidders that you are approaching your limit, which can discourage further competition.
The fake final call. The classic “third and final call” is often repeated multiple times before the hammer actually falls. This is designed to create panic — you think you are about to miss out, so you throw in one more bid. Experienced auction-goers know that the “final call” is rarely final.
The pause and approach. When bidding stalls below the reserve, the auctioneer may pause and consult with the agent or vendor. During this break, agents will often approach the highest bidders for quiet conversations designed to extract one more bid. They might hint that you are very close to the reserve, or that the vendor is considering selling if you just stretch a little further.
Social pressure from the crowd. Having 50 or 100 people watching you creates implicit pressure to keep bidding. Nobody wants to be seen “losing” in public. Some agents deliberately encourage large crowds at auctions — offering coffee, snacks, or making it a community event — precisely because a bigger audience creates more psychological pressure on genuine bidders.
Pre-Auction Offers Are Not Always in Your Interest
If an agent calls you before the auction and suggests you might want to put in a pre-auction offer, be very careful about what information you reveal.
From the buyer’s perspective, a pre-auction offer can sometimes secure a property without the stress and uncertainty of auction day. But from the agent’s perspective, your offer provides incredibly valuable market intelligence. It tells them the minimum someone is willing to pay, which helps the vendor set their reserve price and auction strategy.
Even if your pre-auction offer is rejected, the agent now knows your budget. They know you are serious. And they know roughly where to set the reserve to ensure the property passes your offer on auction day.
If you do make a pre-auction offer: Make it strong enough that the vendor would be foolish to reject it, and set a short deadline for acceptance. Attach conditions if possible (finance, building inspection) because auction contracts are typically unconditional. And understand that if your offer is rejected, you have revealed your hand — the agent will use that information on auction day.
Cooling-Off Periods Usually Do Not Apply
One of the most important things agents will not emphasise is that in most states, there is no cooling-off period for properties purchased at auction. Once the hammer falls and you sign the contract, you are legally bound. There is no five-day grace period, no chance to change your mind, no getting out because your building inspection came back bad.
This means every piece of due diligence — building and pest inspections, strata reports, contract review by your solicitor, finance pre-approval — must be completed before auction day. Not after. If you buy at auction and then discover the property has significant structural issues, that is your problem. The ACCC’s guide to buying property is a useful starting point for understanding your consumer rights throughout the process.
The cost of pre-auction due diligence can add up. A building and pest inspection typically runs $500 to $800, a strata report $200 to $400, and a solicitor’s contract review $300 to $600. If you are bidding on multiple properties before successfully purchasing one, these costs multiply. It is a genuine frustration of the auction system, and agents rarely draw attention to it because it might discourage potential bidders.
Commission Is Negotiable
If you are on the selling side, here is something agents will not volunteer: their commission rate is absolutely negotiable. The standard rate varies by state but typically sits between 1.5 and 3 per cent. On an $800,000 sale, that is anywhere from $12,000 to $24,000.
Agents will often present their rate as standard or fixed, but the reality is that it is a competitive market and agents frequently reduce their commission to win listings. The internet has made their job significantly easier — buyers find properties online rather than through agent databases — yet commission rates have not dropped proportionally.
You should also be aware that some agents charge marketing costs on top of their commission. These can include professional photography, online listings, print advertising, and signage. These costs are payable by the seller regardless of whether the property sells, and can run anywhere from $2,000 to $15,000 or more depending on the campaign.
The Practical Auction Survival Kit
Armed with all of this knowledge, here is how to actually survive — and potentially win — at an Australian property auction.
Before the auction:
- Set your absolute maximum price and write it down. Share it with your partner or a trusted friend who will be with you on the day. Their job is to physically stop you from bidding above this number.
- Complete all due diligence before auction day. Building and pest inspection, contract review by your solicitor, strata report if applicable, and finance pre-approval. Do not skip any of these.
- Research comparable sales obsessively. Know what similar properties in the area have sold for recently. Use this data, not the agent’s price guide, to determine the property’s true value and set your maximum.
- Attend at least three auctions as a spectator before bidding on one. Watch the dynamics, the tactics, and the pressure points. This experience is invaluable.
- Arrange your deposit. You will typically need to pay 10 per cent on the day (sometimes 5 per cent by negotiation). Most agents accept personal cheques, bank cheques, or electronic transfer. Confirm the accepted methods with the agent beforehand.
On auction day:
- Arrive early and observe the crowd. Try to identify other serious bidders — they are usually the ones reviewing the contract one last time or speaking quietly with their partner.
- Register to bid even if you are not certain you will. You cannot bid without registering, and the registration process can take a few minutes.
- Consider opening the bidding. Making the first bid can set the pace and demonstrate confidence. Open at a price that reflects the property’s real value (based on your comparable sales research), not the agent’s inflated starting suggestion.
- Bid in your own increments. If the auctioneer asks for $10,000, you can bid $1,000 or $5,000. Smaller increments slow the auction, rattle other bidders, and preserve your budget.
- Take your time. There is no rule that says you must bid immediately. Pauses unsettle auctioneers and other bidders. Use silence strategically.
- Ignore the assisting agent. Politely but firmly. They are not on your side.
- Walk away if it exceeds your maximum. This is the hardest thing to do and the most important. There will always be another property. There will not always be another $50,000.
If the property is passed in:
If you were the highest bidder and the property did not meet its reserve, you have the right of first negotiation with the vendor. This is actually a powerful position. The vendor has just watched their property fail to sell publicly, which changes the dynamics significantly. Take your time. You are not obligated to increase your bid. Start negotiations from your final auction bid, not from a higher number, and let the vendor come down to meet you.
Consider Hiring a Buyer’s Agent
If the entire auction process sounds exhausting and adversarial — well, it is. One option worth considering is hiring a buyer’s agent (also called a buyer’s advocate). These are licensed professionals who work exclusively for buyers, not sellers. You can find accredited buyer’s agents through the Real Estate Buyers Agents Association of Australia (REBAA).
A good buyer’s agent will handle comparable sales research, identify underquoted properties, manage your bidding strategy on auction day, and negotiate on your behalf if the property is passed in. Their fees typically range from 1 to 2 per cent of the purchase price, or a flat fee of $10,000 to $20,000.
The main advantage is emotional distance. A buyer’s agent will not fall in love with the property. They will not get swept up in the excitement. They will bid mechanically to your maximum and walk away without hesitation if the price exceeds it. For many buyers, that discipline alone is worth the fee.
The Bottom Line
The Australian auction system is exciting, transparent in some ways, and deeply opaque in others. The playing field is not level — agents have more information than buyers, vendors can adjust reserves on the fly, and the emotional pressure of a live auction pushes people to overspend.
But none of this means you cannot succeed. Armed with proper research, a clear budget, pre-completed due diligence, and an understanding of the tactics being used around you, an auction can actually work in your favour. Competition can stall, reserves can be set too high, and well-prepared bidders can secure excellent properties at fair prices.
The key is walking in with knowledge rather than hope. Agents are not going to arm you with that knowledge — it is not their job. So consider this article your briefing before you step onto the battlefield.
And once the hammer falls in your favour, the real work begins. Between settlement timelines, organising your move, and the thousand small tasks that come with taking possession of a property, the weeks after auction day can be just as stressful as the day itself. Getting ahead on the logistics — especially lining up reliable removalists early — takes one major headache off your plate.
Settlement periods vary by state but typically run 30 to 90 days, which sounds like plenty of time until you realise how quickly it disappears. Locking in a removalist early is one of the smartest things you can do, especially in busy auction markets where good movers book out weeks in advance. You can compare quotes from vetted local removalists in Sydney, Melbourne, Brisbane, Adelaide and Perth through Find a Mover — one less thing to stress about while you are counting down to settlement day.
Disclaimer: This article provides general information only and is current as of February 2026. Auction rules and regulations vary by state and territory and can change at any time. Always seek independent legal advice before bidding at auction. This is not legal or financial advice.